Borrowers seeking a loan for farmland purchase often face hurdles if their income does not fit the standard W-2 or simple tax return model. Many established landowners and agricultural property investors earn income from multiple sources, with cash flow that may be seasonal, tied to partnerships, or reflected unevenly on tax forms.
Private lenders like Farm Mortgage Capital look beyond standard paperwork and focus on real repayment capacity, using documentation that captures a broader financial picture. By understanding which records demonstrate income reliability for large, land-backed loans, applicants can prepare a strong, credible case even without traditional tax returns.
Acceptable Proofs: Bank Statements, K-1s, and Financial Records
Three main types of alternative documentation can help a borrower demonstrate repayment capacity for a loan for farmland purchase. Bank statements provide a direct look at cash flow over several months. K-1 forms from partnerships or S corporations show each partner’s share of income, which is useful for applicants with entity-based ownership interests.
Financial records, such as profit and loss statements or rental income statements, give lenders another way to assess regular income when tax returns do not provide a complete picture. The lender will expect these documents to cover a consistent period and support the size of the loan request.
There is often a strong benefit to preparing these records with a CPA’s help, since clarity and consistency are key. Missing or unclear documentation could slow or prevent a farm mortgage approval. The right alternative records can give Farm Mortgage Capital what is needed to evaluate complex income streams for substantial farm mortgage loans in Washington involving $400,000 or more.
How Private Farm Lenders Assess Irregular or Seasonal Income
Private agricultural mortgage lenders use several strategies to evaluate irregular or seasonal income when considering a loan for farmland purchase.
Income pattern review: Lenders may look for income patterns across several months or years. Even if revenue is seasonal, showing repeated income patterns and consistent financial activity can help establish repayment capacity.
Entity-based income analysis: When income comes from partnerships or multiple business entities, lenders may require detailed statements showing each owner’s share. These records help verify the applicant’s financial interest and access to the reported income.
Seasonal adjustment of cash flow: Lenders may adjust their review period to account for income fluctuations throughout the year. This approach gives a fuller picture of the borrower’s financial position, which is important when evaluating substantial agricultural land mortgage applications.
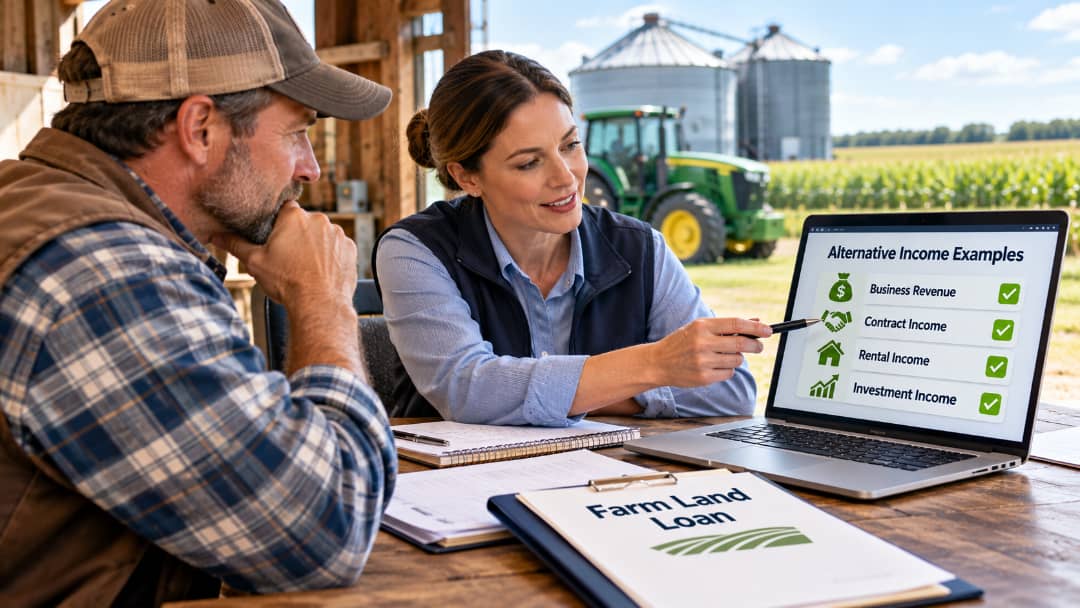
Verification of additional income: If an applicant has other income streams, such as rental or investment income, lenders may request clear, separate documentation. This helps establish that the income is legitimate, verifiable, and available to support loan payments.
Extra documentation requirements: Because income may not follow a standard W-2 pattern, lenders may request more records to establish repayment capacity. Preparing organized, comprehensive documents will reduce delays and help prevent approval setbacks.
Leveraging Collateral Strength When Income Shows Complexity
Collateral value becomes a critical factor when income documentation is complex or irregular.
Significant farmland equity and valuable agricultural real estate can strengthen a mortgage application when traditional income verification presents challenges. For private lenders, the property’s appraised value, ownership structure, and available equity are important considerations when evaluating substantial land-backed financing.
A substantial down payment or significant existing equity can strengthen the overall application when income streams are seasonal or distributed across multiple entities. By reducing the amount financed relative to the property’s value, these factors may support the lender’s risk assessment. However, collateral strength does not automatically replace the need to demonstrate repayment capacity.
Providing thorough documentation of land value, such as recent appraisals or detailed property records, further supports the application. When collateral provides sufficient security relative to the loan amount and offers a reasonable buffer against market changes, lenders can better assess requests involving complex income profiles.
Documenting Consistent Income to Support Agricultural Property Financing
Several types of documentation help establish financial consistency when borrowers have multiple income sources. Lenders want to see that income is not just a one-time event but can be verified across relevant periods. A clear paper trail from property leases, rental agreements, investment distributions, and other documented income sources will show how various financial streams contribute to overall repayment capacity.
The key is consistency. Each income source’s records need to line up with bank deposits and match the timing of the reported payments. Organized statements prepared by a CPA or bookkeeper can help connect the financial records for an underwriter.
The more direct and verifiable the evidence, the easier it is for Farm Mortgage Capital to assess real repayment capacity for substantial land-backed loans. This approach allows borrowers with diverse financial profiles to present a clearer picture of their ability to support agricultural real estate mortgage payments, even when standard tax returns do not reflect their full financial position.
For anyone managing multiple income streams, preparing detailed, cross-referenced records in advance can make a big difference in the approval process.
Borrowers with nontraditional income streams face several key questions when preparing for substantial farmland mortgage approval. Which alternative records will a lender accept to demonstrate reliable income? How does a private lender verify seasonal or entity-based earnings?
What role does strong collateral play if income documentation is complex? Which documentation gaps could delay approval, and how can borrowers address them? Acceptable proofs may include bank statements, partnership K-1s, and detailed financial records, each covering a consistent period and supporting the requested loan amount.
For complex, seasonal, or multi-entity income, providing organized, CPA-prepared records and clear collateral documentation gives Farm Mortgage Capital the information needed to evaluate repayment capacity for agricultural real estate mortgage transactions of $400,000 or more.
This approach helps ensure applicants are better prepared for the underwriting process, even without standard tax returns.